
Mortgages, more advice and transparency: the role of Credit Brokers
Susanna Fiorletta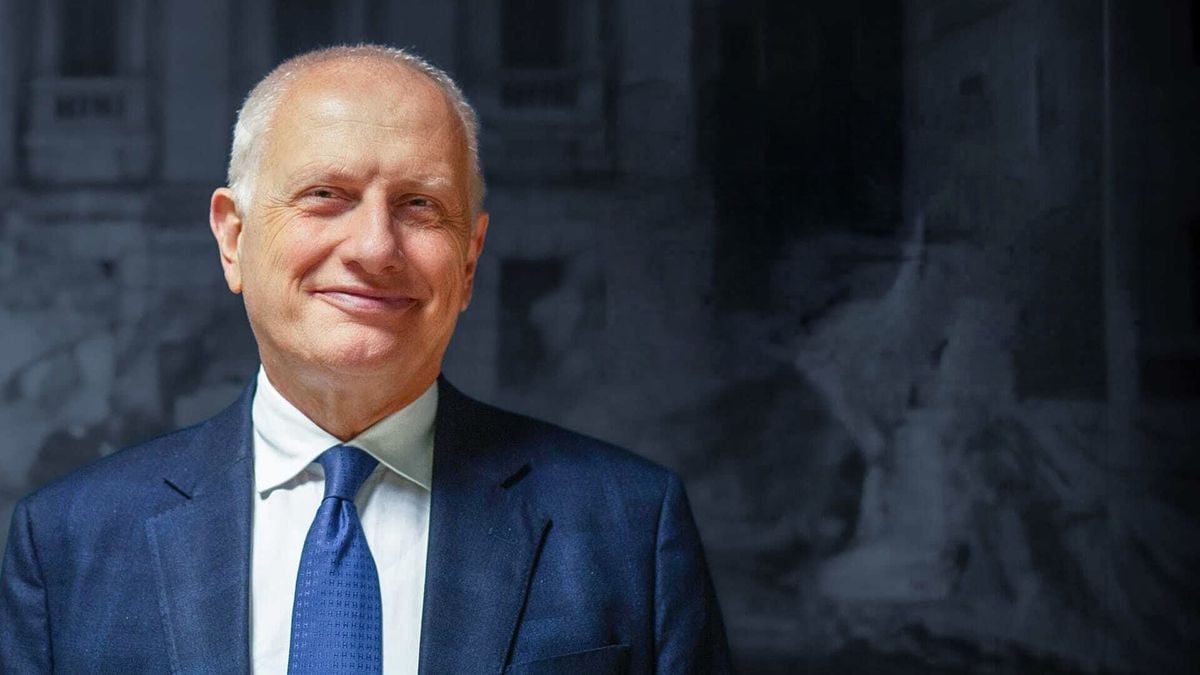
The ECB raises interest rates, while the mortgage market remains stable. In this context, credit brokers are taking on an increasingly central role: they guide clients through different offers, identify sustainable solutions and facilitate relationships with lending institutions.
Interview with Federico Luchetti, General Manager of OAM
Let’s start with a brief analysis of the current credit environment: the recent interest rate increase decided by the ECB on 10 September has once again drawn attention to the mortgage market. What scenario has this decision created?
The mortgage market is influenced by many variables, not just the level of interest rates. If we look at what happened after the similar 25-basis-point increase decided by the ECB in June, we do not see any significant impact.
The latest data from the Bank of Italy, published in September, show that in July the Annual Percentage Rate of Charge (APRC) on new loans to households for house purchases stood at 3.81%, compared with 3.95% in the previous month. Overall, loans to households also increased by 2.6%, compared with 2.7% in the previous month.
The bank lending survey for the euro area, published in July by the Bank of Italy, also reports that, according to the banks surveyed, lending standards for residential mortgages remained unchanged in the second quarter of 2026, while standards for consumer credit were tightened further. For the current quarter, banks instead expect a moderate tightening of lending conditions for households.
At present, we can say that the sector does not appear to be significantly affected by restrictive monetary policy. Its effects will need to be assessed over the coming months.
According to the latest OAM-Prometeia Report, third-party distribution networks account for around 42% of the residential mortgage market, with credit brokers representing 34%. What does this figure tell us about how the relationship between clients and industry professionals is evolving?
I believe this figure can be interpreted in two ways: on the one hand, it is the result of the evolution of the credit market, which has seen the number of bank branches decrease over the years. This "gap" has been filled by credit professionals: over the past 10 years, the ratio between the "third-party" workforce and bank employees has shifted from approximately 1 credit professional for every 20 bank employees to 1 credit professional for every 10 bank employees.
Alongside this "substitution" effect, there is also the advisory role played by brokers, who support clients in choosing a mortgage that is financially sustainable and tailored to their individual needs.
With Legislative Decree 212/2025, Italy officially implemented the new European Consumer Credit Directive (CCD2), aimed at strengthening consumer protection, transparency and creditworthiness assessment. What are the main changes for the sector, and how does this affect the way credit brokers are expected to support clients?
If I had to choose one keyword for the new regulatory framework, I would choose "over-indebtedness". This is the real focus around which the European framework revolves: it is no coincidence that, when implementing the Directive, the Italian legislature extended the Organisation’s supervisory powers to sectors such as merchants, namely large retail chains and online sellers, which previously represented a grey area that could contribute to increasing consumer debt.
From the perspective of real estate credit, the area in which brokers are most active, the implementation of the Directive aligned the rules governing consumer real estate credit agreements with the general framework for consumer credit agreements, with the aim of raising the level of consumer protection: this includes debt advisory services, the new rules governing databases, creditworthiness assessment, which applies to all credit agreements, and the extension to real estate credit agreements of the invalidity regime where contractual clauses differ from the financial terms communicated to the consumer in the personalised information provided.
As for the way brokers are expected to support clients, the real innovation introduced by the legislation is the strengthening of brokers’ supervisory obligations over their collaborators, together with direct OAM supervision of the collaborators themselves. This is an important development because it encourages transparent and responsible conduct among credit professionals.
In today’s market, clients are often faced with many different offers, with terms, costs and parameters that are not always easy to compare. What makes financial advice truly comprehensive? And what added value does a credit broker bring to the relationship between clients and lending institutions?
The role of credit brokers is precisely to help people looking for financing find the solution that best suits their individual needs, especially in terms of sustainability.
I would add that advice is truly comprehensive when the broker clearly explains that some lenders fall outside the scope of their research. Transparency must be absolute.
As for added value, in addition to guiding clients towards the most suitable choice, brokers know which documents are required by banks and can certainly help speed up the application assessment process.
OAM consistently highlights the importance of transparency, professional training and action against unauthorised activity. How do these safeguards strengthen confidence in the market and help establish the credit broker as a trusted point of reference for consumers?
A supervised market focused on protecting consumers and competition, where operators that do not meet the required standards cannot conduct business, is an essential condition for ensuring that the credit system functions responsibly and contributes to the country’s growth. The Organisation is strongly committed to achieving this objective, also thanks to the new powers granted to it through the implementation of CCD2.
OAM’s ability to supervise collaborators directly, together with the creation of a dedicated database for market operators in which the names of collaborators who have failed to comply with regulations will be recorded, strengthens consumer protection safeguards and confidence in the market.
Knowing that the credit sector is made up of qualified professionals, subject to rigorous ongoing training and integrity requirements monitored by an authority, creates the confidence needed to prevent consumers from turning to "alternative" channels that may put the sustainability of their debt at risk.
Explore the content you want to learn more about
Editorials
Editorials by the President Ilario Antonio Toscano
16 News
Observatory
Real estate analysis, data, and trends
13 News
Gruppo Toscano World
All articles related to Gruppo Toscano world
34 News